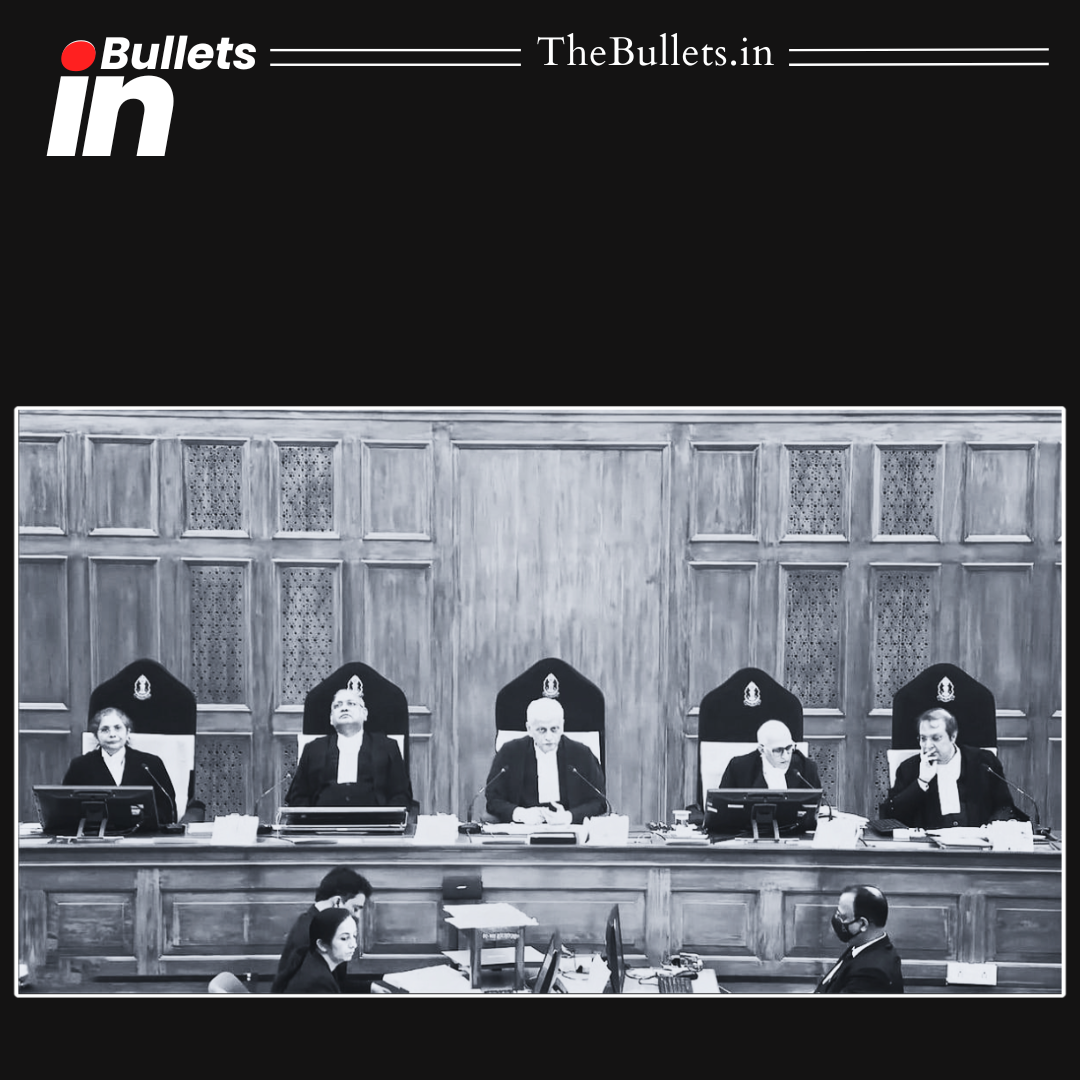

A seven-judge Constitution Bench reserved judgment on 22 September in Arjun Flour Mills v State of Orissa, which tests whether states can levy surcharges calculated on sales tax.
BulletsIn
- On 22 September 2026, a seven-judge Constitution Bench led by CJI Surya Kant reserved judgment in Arjun Flour Mills v State of Orissa.
- The Bench also included Justices K.V. Viswanathan, S.V. Bhatti, Joymalya Bagchi, N.V. Anjaria, Arun Palli and V. Mohana.
- The case concerns Section 5A of the Orissa Sales Tax Act, 1947, inserted in 1997, which imposed an additional tax on dealers based on annual turnover.
- The levy was 10% for dealers with turnover between ₹10 lakh and ₹1 crore, and 15% where turnover exceeded ₹1 crore.
- The core question is whether a surcharge or additional tax calculated on a validly levied sales tax falls outside State competence under Entry 54 of the State List.
- The alternative argument is that such a levy encroaches on Entry 82 of the Union List, which covers taxes on income.
- In Hoechst Pharmaceuticals v State of Bihar (1983), the Court upheld a surcharge as partaking of the nature of sales tax, on a concession that it related to Entry 54.
- In India Cements v State of Tamil Nadu, a seven-judge Bench struck down a cess on mining royalty, holding a State could not legislate outside its Seventh Schedule field.
- S. Kodar v State of Kerala, decided by five judges, upheld an additional sales tax and rejected the argument that it was a tax on income.
- Faced with these divergent rulings, the Court first sent the matter to a larger Bench in August 1998, and it was listed before seven judges in October 1999.
- The case stayed in limbo until October 2023, when the Court said it would take it up with other pending seven-judge matters.
Tags: ArjunFlourMills, ConstitutionBench, SalesTaxSurcharge

What do you think?
It is nice to know your opinion. Leave a comment.